How to Get a Portuguese NIF From Abroad: Free In-Person Filing, e-balcão via a Legal Representative, and Paid Agencies
A fact-checked guide to getting a Portuguese NIF as a non-resident, following Autoridade Tributária’s official leaflet: apply free in person at Finanças or a Lo
What this covers
A Portuguese tax identification number, or NIF (Número de Identificação Fiscal, also called número de contribuinte), is issued by Autoridade Tributária e Aduaneira (AT, the Tax and Customs Authority). It has nine digits, the last of which is a check digit. The official leaflet says the same number stays with you even if your registration later changes from non-resident to resident.
AT describes a NIF as a prerequisite for many everyday acts, not only tax filings: employment, contracts, opening a bank account, and social security. gov.pt also lists buying goods or services, signing contracts, and opening bank accounts. Owning property in Portugal, registering a vehicle there, signing a local employment contract, or carrying on a self-employed activity can also create a legal tax relationship with AT. A telecom or eSIM provider may ask for a NIF when you sign a contract; that is a matter for the operator's contract, not a separate AT rule written for eSIMs.
A NIF is not a residence permit or a work visa, and holding one does not make you a Portuguese tax resident.
If you are not in Portugal, there are three usual routes:
- Book an appointment and apply in person at any Serviço de Finanças (tax office) or Loja do Cidadão (Citizen's Shop). Official pages state that applying for the NIF itself is free.
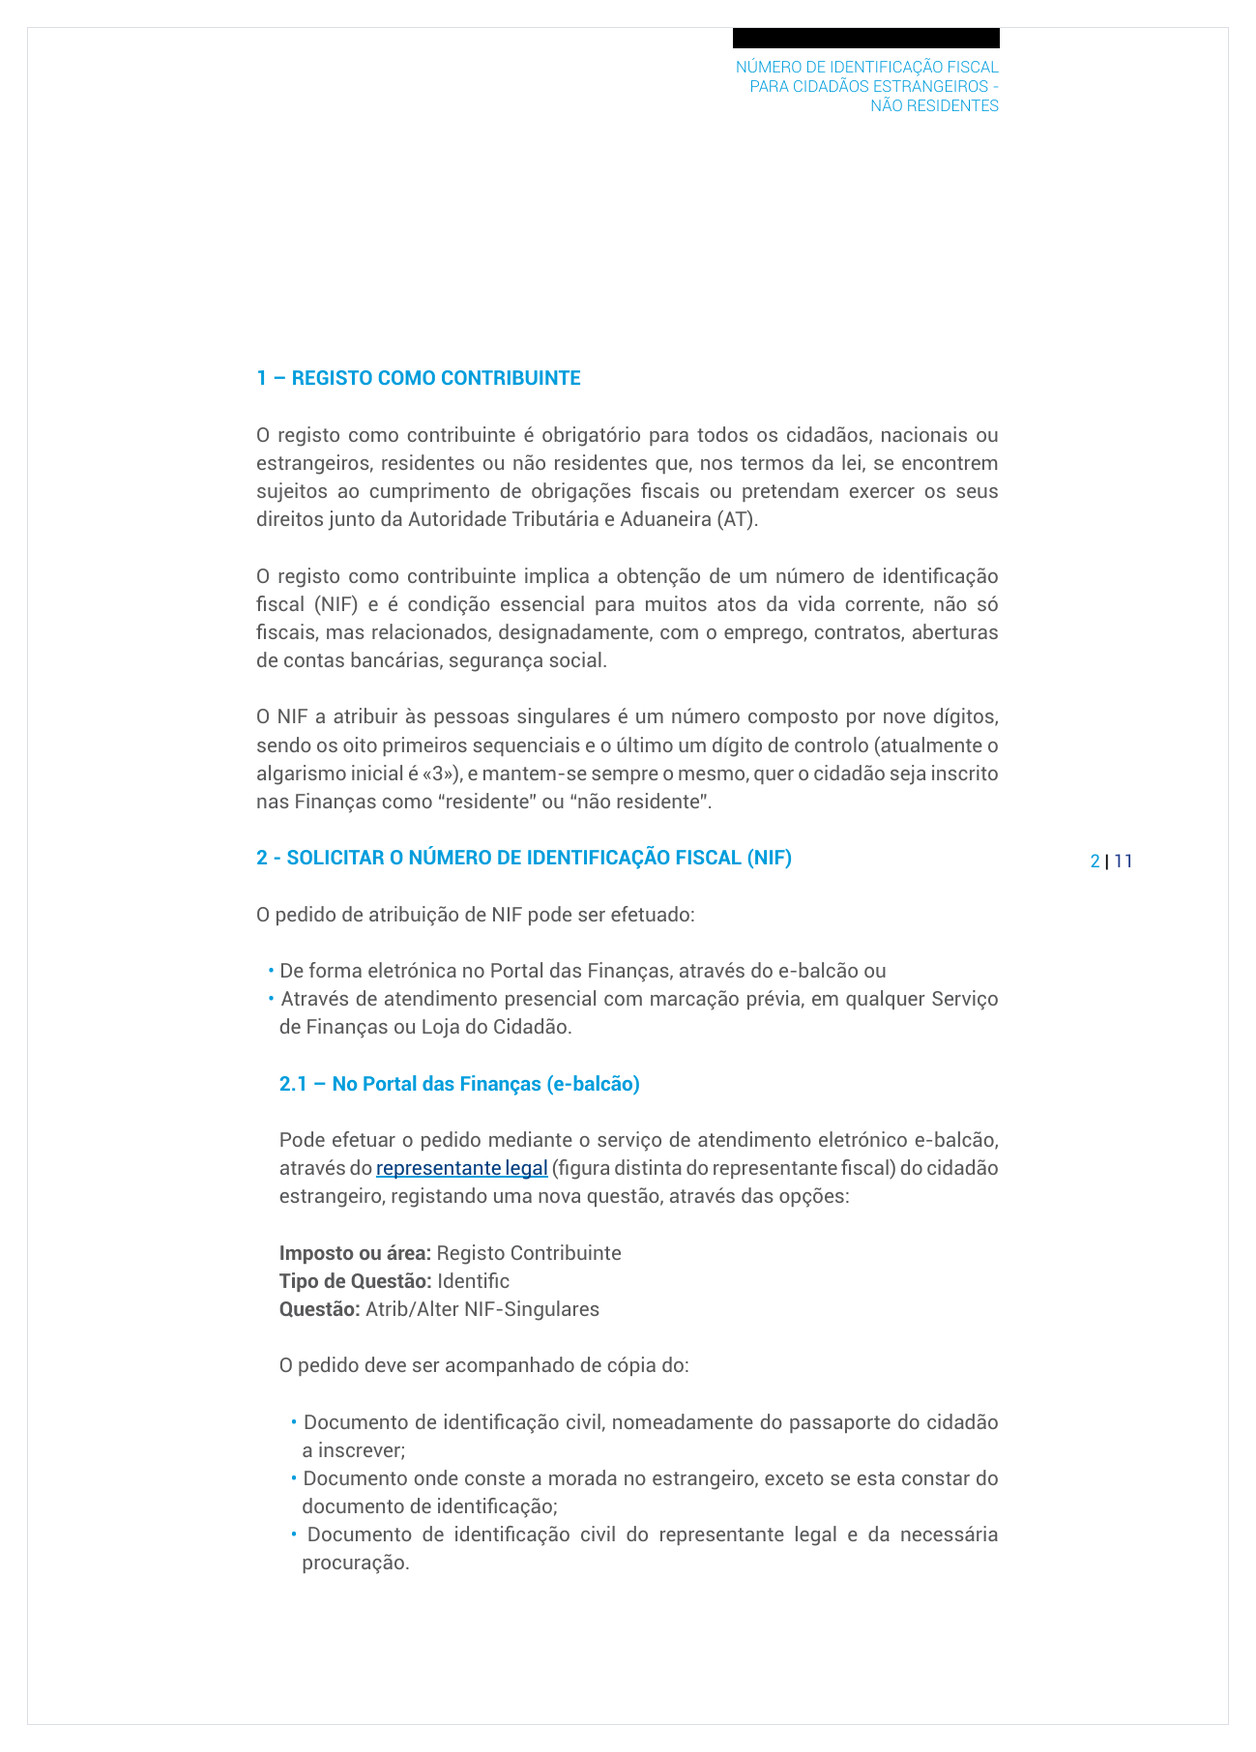
- Have a legal representative (representante legal / attorney-in-fact — not the same role as a fiscal representative) log into Portal das Finanças and file through e-balcão.
- Use a paid third-party agency. The source post describes NIF Online, which is not a government site. Its price is a service fee, not a tax.
This standalone guide expands section 3 of the published article no. 134, “Four ways to apply for Malaysian, Italian, Portuguese and German tax IDs”, and follows the same idea as the German tax-ID guide no. 139. Article 134 already covers the NIF Online agency route; this piece adds the official in-person and e-balcão paths, plus the rules on fiscal representatives and electronic notification. It does not replace article 134.
The source is a 10 November 2026 (UTC) explainer by @artistd4qu about NIF Online. It has no referral code. This guide does not invent hands-on testing. Documents, deadlines and fees follow AT, gov.pt, and the agency page you see before you pay.
Before you start
Keep three distinctions clear:
- The official application is free. gov.pt states “O pedido do NIF é gratuito.” An agency charges for its service; that is not an AT fee for the number.
- A legal representative is not a fiscal representative. In the AT leaflet, the person who files through e-balcão is a legal representative or attorney-in-fact (representante legal / mandatário / procurador). A fiscal representative (representante fiscal) is a separate role, used to receive tax-authority mail and meet accessory tax duties. The leaflet says that when a foreign national is registered as a non-resident and given a NIF, appointing a fiscal representative is not required.
- gov.pt's short pages and the AT leaflet do not use exactly the same wording. The brief gov.pt guide for foreign nationals lists “a fiscal representative with a Portuguese address” among the documents for non-residents. AT's more detailed non-resident leaflet, and AT's English page Appoint a tax representative, both say you can request a NIF without appointing one at the same time. If you later establish a tax relationship with Portugal, you may then have to appoint a representative or join electronic notifications. Where the wording conflicts, follow the AT non-resident leaflet and Article 19 of the General Tax Law (Lei Geral Tributária) as in force, and re-check the official pages on the day you apply.
State a real purpose and a real address. The purpose is recorded in your tax file: do not pick “buying property” just to open a bank account, and do not invent a Portuguese address. Your name, passport number and date of birth must match the passport. Mistakes enter the official record and are hard to fix later.
For an in-person appointment, documents in a foreign language generally need a certified translation. The AT leaflet says documents should be originals or certified copies; plain copies are accepted only when the originals are shown at the same time.
Steps
1. What a NIF is, and when people need one
Typical, realistic uses include signing a contract in Portugal, opening a bank account, taking up employment, dealing with social security, and meeting tax obligations in Portugal. If you later own property there, register a vehicle, sign an employment contract, or start a self-employed activity, AT treats that as a legal tax relationship. You may then have 15 days to appoint a fiscal representative or join electronic notifications.
Getting a number “just in case” does not by itself give you residence rights, a bank account, or tax residence. Banks, operators and agencies can still ask for proof of address or a visa. If you have no genuine use for a NIF, think twice before applying.
2. Route 1: apply in person at Finanças or a Loja do Cidadão, for free
This is the official route if you are in Portugal. The AT leaflet and Portal das Finanças agree: you can go to any Serviço de Finanças or Loja do Cidadão, and you must book ahead.
How to book:
- On Portal das Finanças, open Contactos → Atendimento por Marcação and choose “Para pedido de NIF ou alteração de morada para pessoas sem cartão de cidadão.” Set the subject to Identificação, the sub-subject to Pedido de NIF, and put your ID document number in the notes.
- Or call the tax-authority phone centre, CAT, on (+351) 217 206 707, weekdays 9:00–19:00.
Bring on the day:
- A valid identity document, usually a passport for foreign nationals.
- Proof of your address abroad, unless that address already appears on the identity document.
If you are a third-country national applying in person as yourself, the AT leaflet also expects the passport to show an entry visa for Portugal. An entry visa for any EU country, or visa-free entry to the Schengen Area for your nationality, is treated as an exception. gov.pt's shorter page simply says that if you present a passport you must also present an entry visa for Portugal or the Schengen Area. Follow the desk's instructions and the AT leaflet on the day.
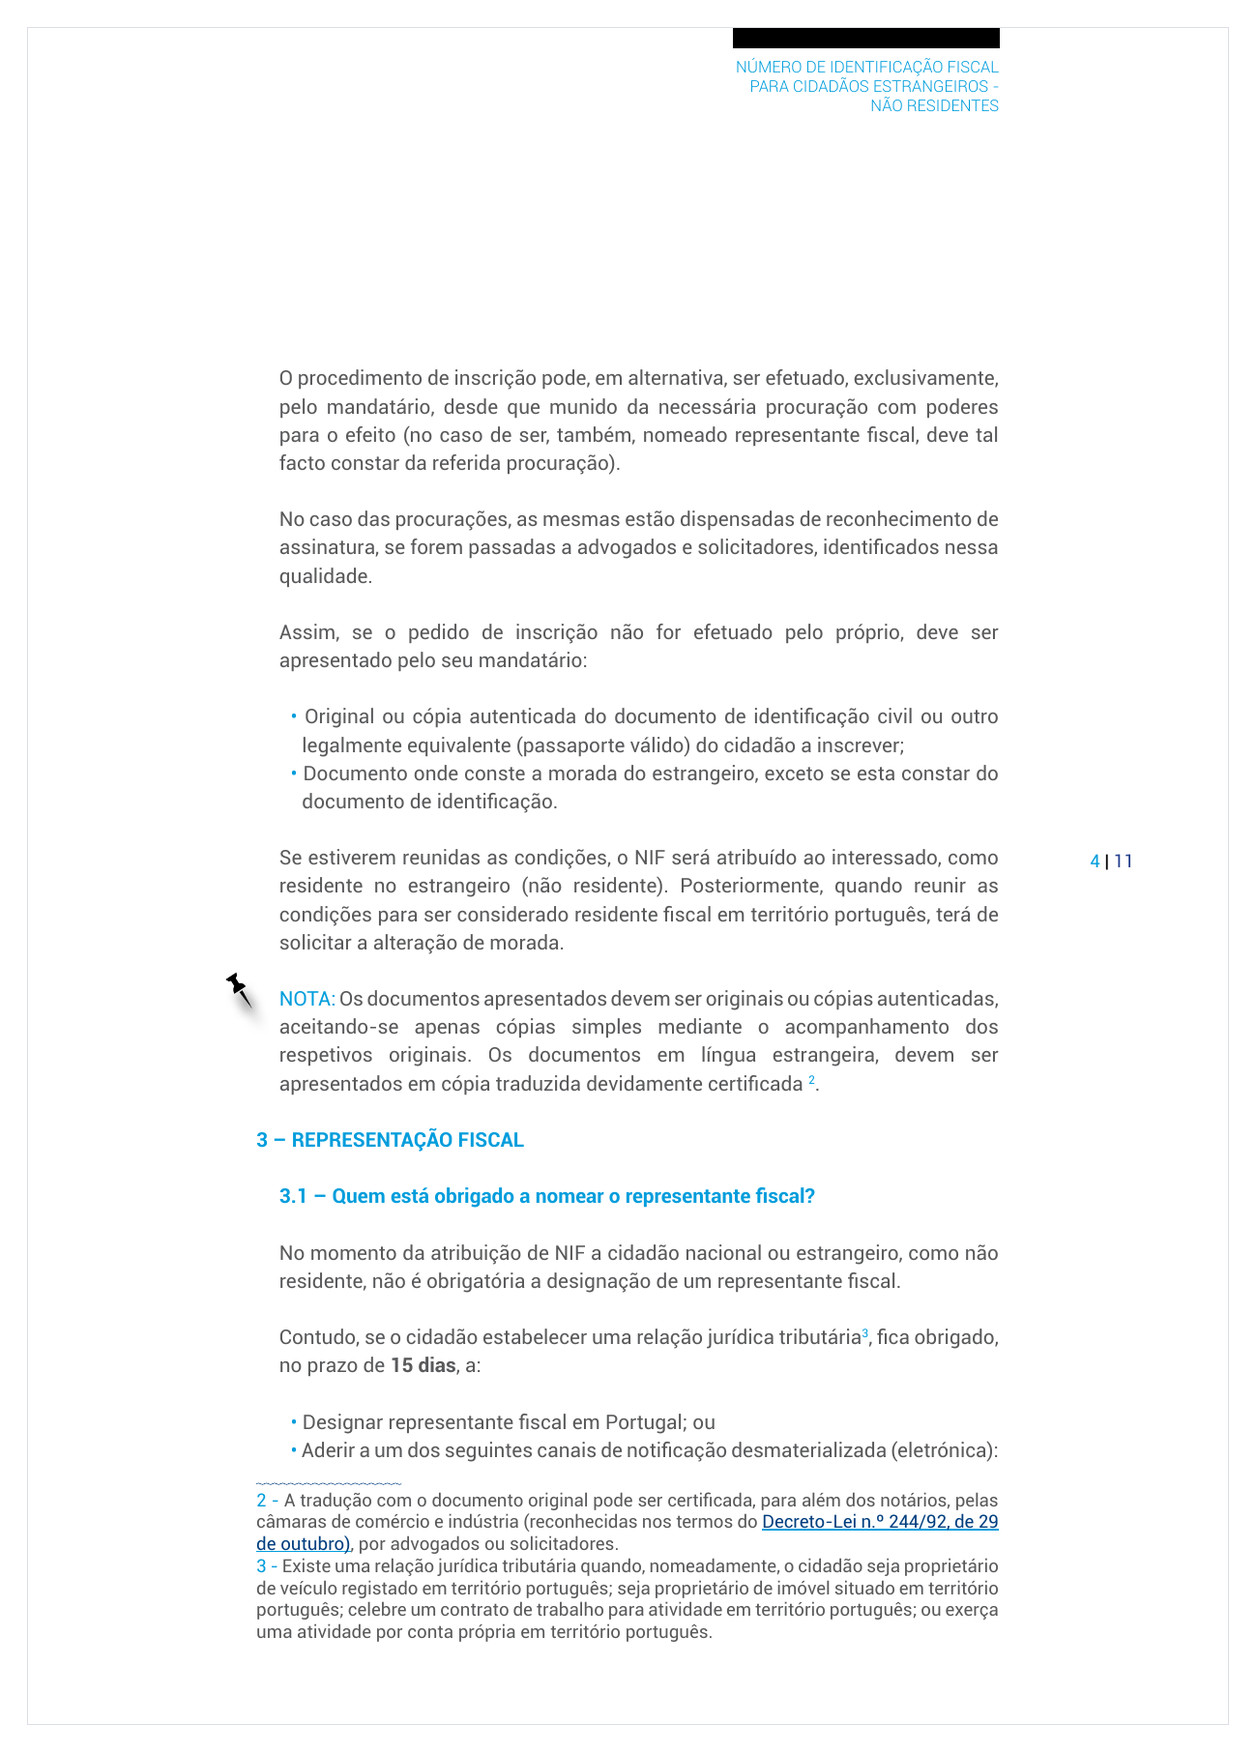
Someone else can file for you if they hold a power of attorney (procuração) granting powers for that purpose. A power of attorney issued to a lawyer (advogado) or solicitador, identified as such, does not need a notarised signature. If that person is also being appointed as your fiscal representative, that fact must be written into the power of attorney.
If the conditions are met, the NIF is issued with you registered as living abroad (non-resident). If you later meet the tests for Portuguese tax residence, you must apply to change your address; do not leave a non-resident registration in place as a fiction.
3. Route 2: from abroad, a legal representative files through e-balcão
If you are not in Portugal, the official online path is not a public self-service form on the tax-authority website. A legal representative who can already log into Portal das Finanças files through the electronic counter, e-balcão.
The AT leaflet gives these options:
- Imposto ou área: Registo Contribuinte
- Tipo de Questão: Identific
- Questão: Atrib/Alter NIF-Singulares
Attach copies of:
- The applicant's identity document, usually a passport.
- Proof of the address abroad, unless it already appears on the identity document.
- The legal representative's own identity document, and a power of attorney granting the relevant powers.
The power of attorney must authorise the representative to apply for the NIF. If it is issued to a lawyer or solicitador identified as such, a notarised signature is not required. If the same instrument also appoints that person as fiscal representative, say so clearly — but that appointment is not a condition for being given a NIF.
AT does not charge a fee for the number on this route. Anything you pay a lawyer or attorney-in-fact is a private fee, not a government tariff. One gov.pt page describes e-balcão filing as being for people who live outside the EU (the wording also mentions Norway, Iceland and Liechtenstein). The exact scope follows the e-balcão page on the day and the AT leaflet.
4. Route 3: a paid agency, with NIF Online as the example
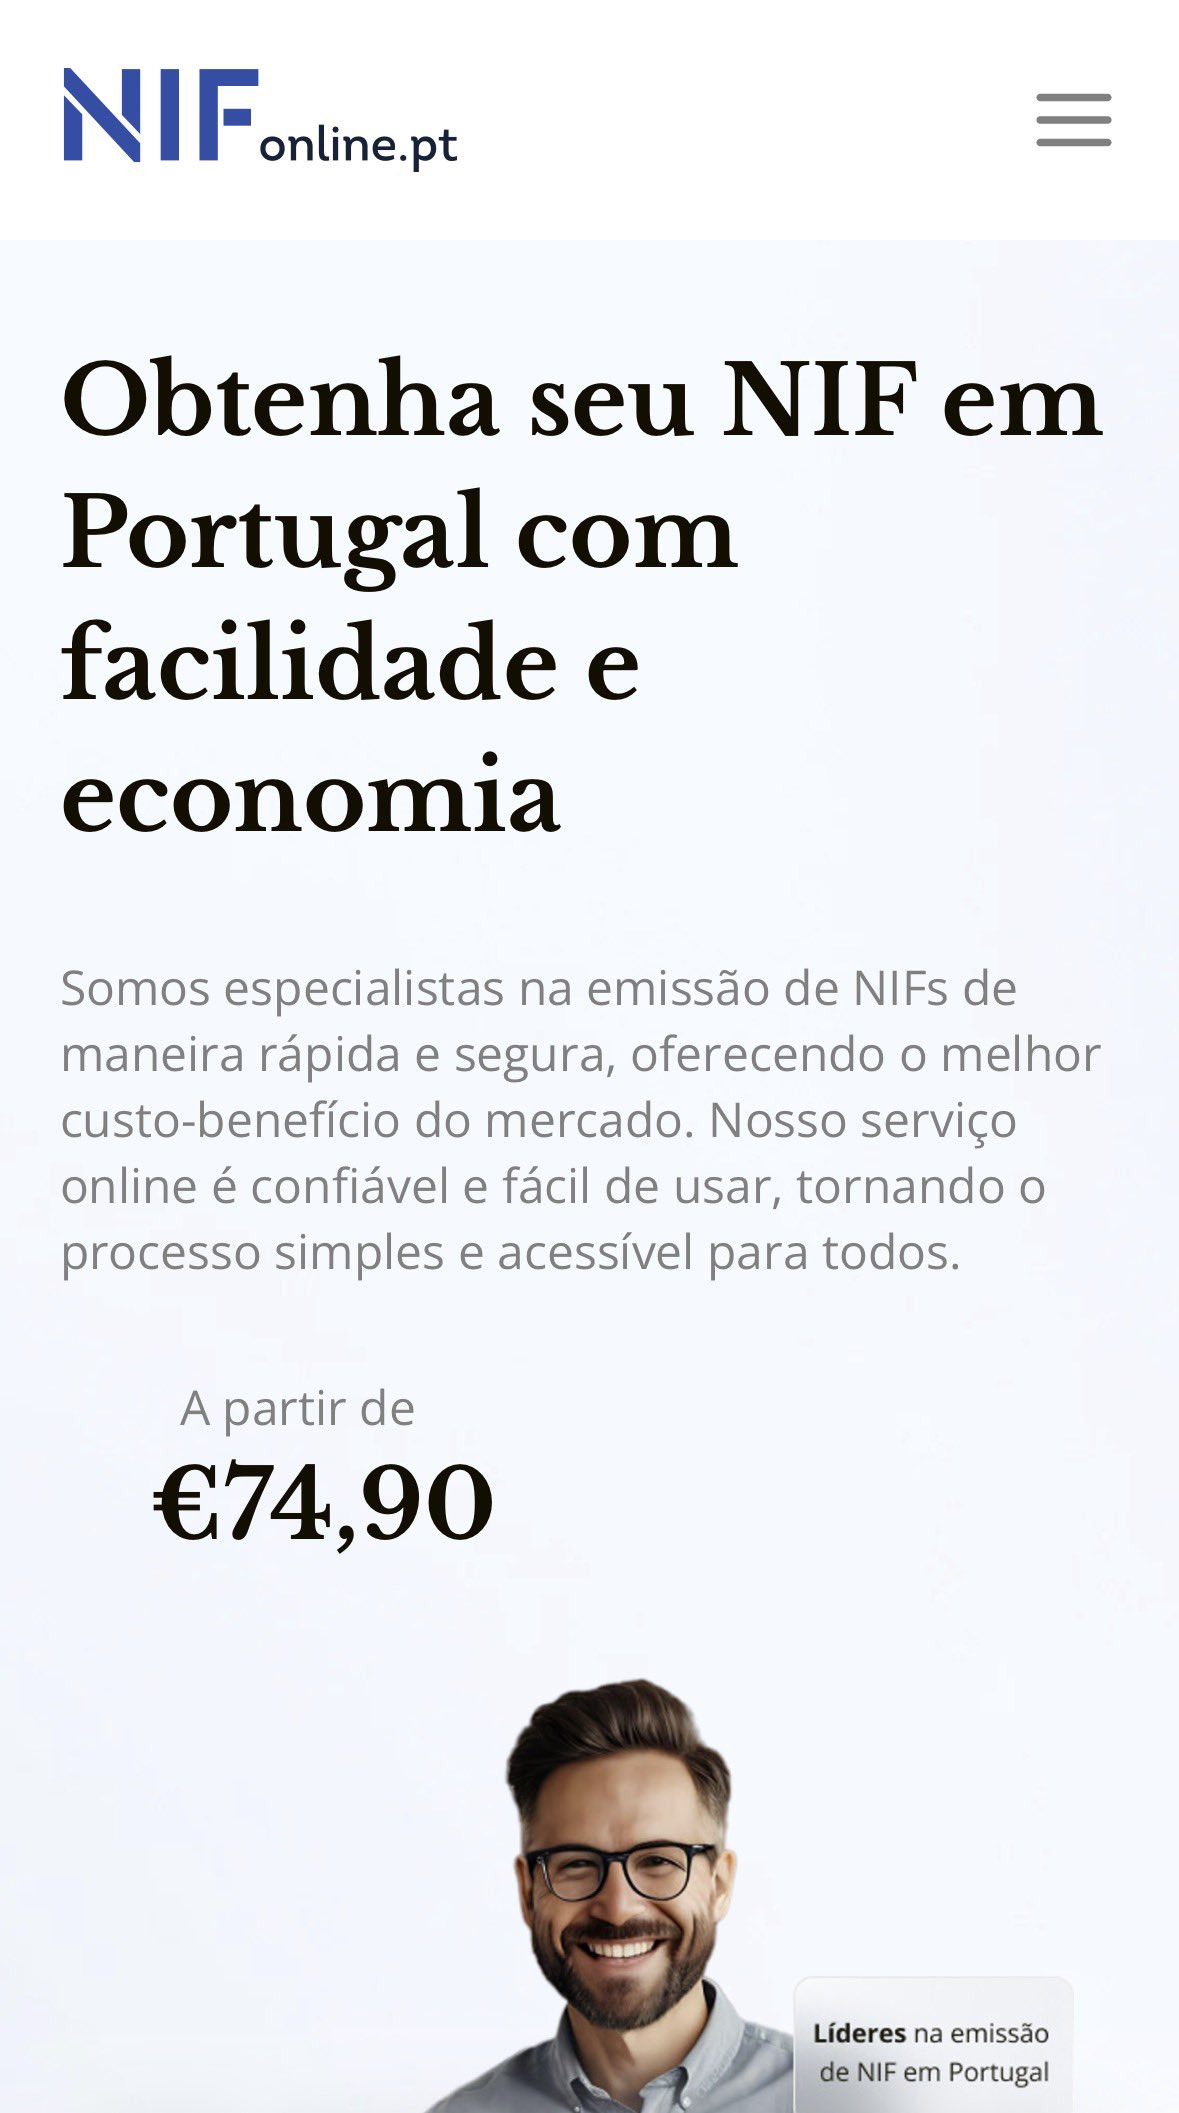
The source post uses the third-party site nifonline.pt, not Portal das Finanças or gov.pt. The post already warns that a platform's claim that “no fiscal representative is needed” does not mean every applicant is exempt, and that €74.90 is the platform's quote, not a government tariff.
The flow in the post is: register with your usual email → choose a NIF for an adult over 18 → enter the purpose, name, date of birth, passport and current real address → check the details and pay → keep the inbox open and wait for the platform to send the documents and the NIF. The post also says the platform later sends a power of attorney for you to sign, then files with AT in your name. Those steps follow the site as it stood at the time of the post. This guide did not register or pay on your behalf, and does not treat the source post as a hands-on test.
On price, keep the layers separate:
- The source image and the homepage copy both say “A partir de €74,90” (from €74.90). A check of the site's current page assets on 11 November 2026 (UTC+8) still showed that figure as the homepage starting price. It is an agency starting fee, not a tax and not an AT charge.
- The site's own service catalogue also lists tax representation, with 12 months free and a choice of automatic renewal or no automatic renewal. Catalogue and subscription entries show €99 and €99.90. Those are the platform's own service prices, not a government fee, and they are not a guarantee of what you will be charged at checkout. This guide did not complete a checkout. Whether they are appointed as your fiscal representative, whether renewal is automatic, and what you actually pay, follow the checkout page and the authorisation or contract you sign.
- Some users have later reported being asked to renew fiscal representation, and some comments discuss a renewal around €99.90 and scores on third-party review sites. Treat those as user or third-party comments, not official rules, and check the contract yourself.
Before you pay, read the scope of the authorisation, whether the agency will be registered as your fiscal representative, whether the plan auto-renews after the first year, how to cancel, and the refund rules. If you do not need a fiscal representative, do not accept automatic renewal just because a bundle includes “12 months of representation.” If you do need one, confirm that the person or firm has a tax domicile in Portugal, and that you can see the appointment in Portal das Finanças.
Choose a genuine purpose, such as opening an account, renting or buying property. The source post warns against picking a purpose for convenience. A real address outside Portugal is acceptable; a made-up one is not.
5. When a fiscal representative is required, and when electronic notification can replace one
Section 3 of the AT leaflet is explicit: when a national or a foreign national is given a NIF as a non-resident, appointing a fiscal representative is not required.
If you later establish a legal tax relationship, you generally have 15 days to do one of the following:
- Appoint a fiscal representative with a domicile in Portugal (a person's address or a company's seat); or
- Join electronic notifications: the electronic notifications and summons system on Portal das Finanças (NCEPF), or the ViaCTT electronic mailbox (caixa postal eletrónica). Article 19(15) of the General Tax Law also lists the public electronic-notification service linked to the single digital address (Morada Única Digital) as a channel that can lift the duty to appoint a representative. The leaflet's main text focuses on Portal notifications and ViaCTT.
The leaflet's examples of a tax relationship include owning a vehicle registered in Portugal, owning property there, signing an employment contract to work there, or carrying on a self-employed activity there.
Note the exceptions:
- For residents of the EU, Norway, Iceland or Liechtenstein, and for Andorran citizens living in Andorra, appointing a fiscal representative or joining electronic notifications is optional, not mandatory. AT's English page also lists Switzerland in the optional group. Follow the official page in force at the time.
- If you live in a third country (outside the EU / the EEA states named above; the leaflet also includes Andorran citizens in this paragraph) and you will carry on a self-employed activity in Portugal, you must still appoint a VAT fiscal representative even if you have joined electronic notifications. That representative must be a VAT taxpayer with a domicile in Portugal, and the appointment must be made before the activity starts. This is a special VAT-code rule; electronic notification does not replace it.
Officially, a fiscal representative receives correspondence from the tax authority (you are treated as domiciled at the representative's address), meets accessory tax duties including filing income-tax returns, and exercises your rights before AT, such as administrative complaints, hierarchical appeals or court challenges. The representative is not usually liable for your taxes. If a non-resident carries on a VAT-taxable self-employed activity in Portugal, though, a VAT representative may be jointly liable for VAT.
Failing to appoint a representative when one is required, or appointing one without the representative's express acceptance, can lead to a fine of €75 to €7,500 (Article 124 of the General Regime of Tax Offences, RGIT). When a representative is mandatory, you also cannot exercise rights before AT, including complaints and appeals, until one is appointed. That bar on exercising rights does not apply to EU / EEA residents.
6. How to appoint, change or end a fiscal representative
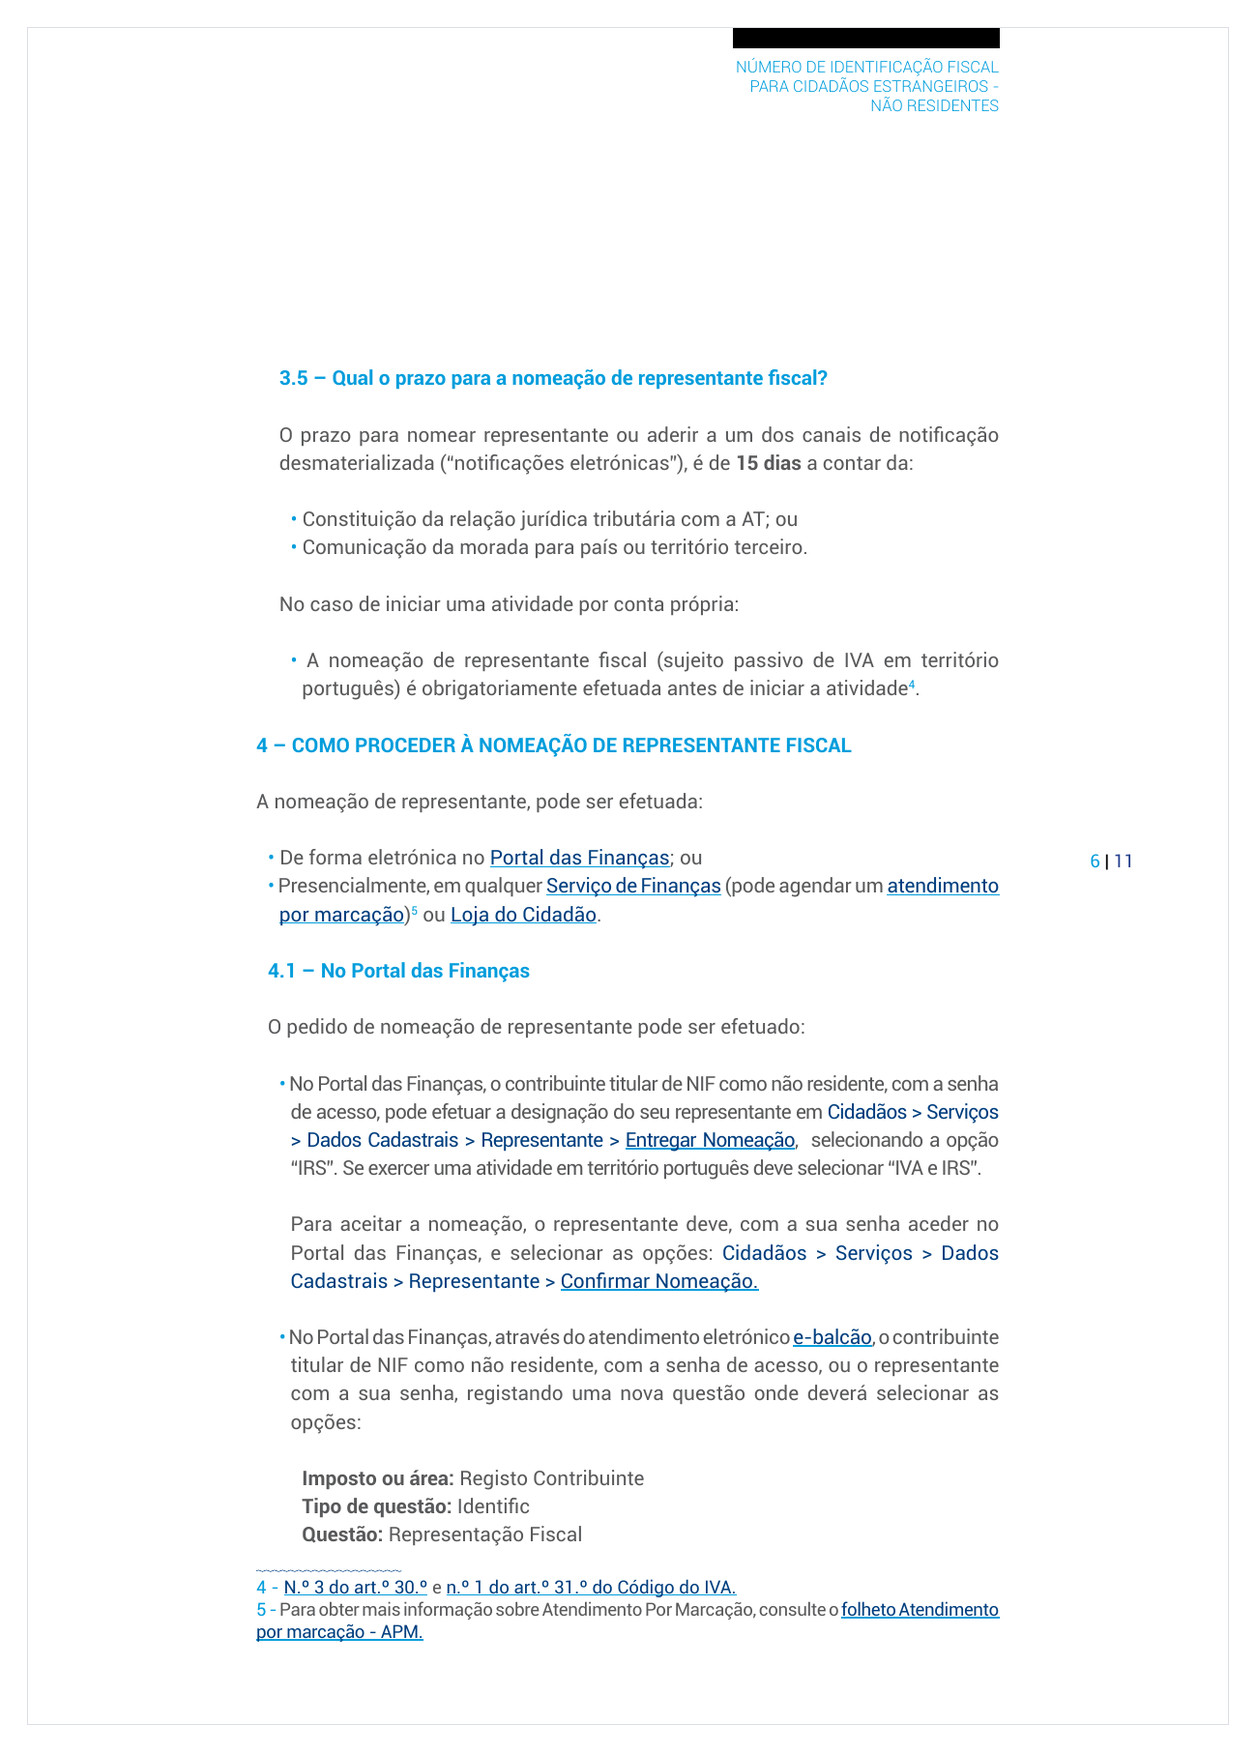
AT's English page and the leaflet describe the same official channels.
On Portal das Finanças, both you and the representative need login credentials (a senha) or a Digital Mobile Key (CMD):
- To appoint or change: after logging in, go to Cidadãos → Serviços → Dados Cadastrais → Representante → Entregar Nomeação. Choose IRS, or IVA e IRS if you carry on an activity in Portugal. After you identify the representative and the scope and submit the request, the appointment is complete only when the other party accepts it.
- To accept: the representative logs in and confirms under Confirmar Nomeação on the same path. Official FAQs also say AT sends the nominee a confirmation code, and the appointment takes effect only once that code is entered. If the nominee neither accepts nor acts, the nomination expires after 30 days. Changing an existing representative uses the same “submit a nomination” flow.
- You can also use e-balcão: Registo Contribuinte → Identific → Representação Fiscal. If the non-resident files, attach a declaration of acceptance signed by the representative. If the representative files, attach a power of attorney from the non-resident granting powers for that purpose. Documents in a foreign language need a certified translation.
You can also book and attend a Serviço de Finanças or Loja do Cidadão together. If the non-resident cannot attend, the representative may go alone with a suitable power of attorney.
If the representative wants to resign, Articles 19(9) and 19(10) of the General Tax Law apply: the representative must give written notice to the represented person at their last registered address. The resignation takes effect vis-à-vis AT only when AT is notified. AT then has 90 days to make the change, provided at least one year has passed since the appointment or a new fiscal representative has already been appointed. AT's 2019 circular (Ofício-circulado 90026/2019) adds that the one-year / new-representative condition applies mainly to third-country non-residents; for EU / EEA residents, resignation takes effect once it is notified to AT with proof that the represented person was informed. The circular treats a registered letter with advice of receipt as an appropriate method, and the proof of posting and receipt should be shown at Finanças or a Loja do Cidadão.
Separately, under Article 19(16), a non-EU / non-EEA resident who wants to cancel electronic notifications must appoint a fiscal representative first; only then does the cancellation take effect.
Agencies such as NIF Online may also sell a service to help you withdraw a fiscal representative. Their copy has mentioned a fee of about €49.90 plus VAT where applicable, and assistance with activating electronic notifications and filing the withdrawal with AT. That is a commercial service. Whether the withdrawal is accepted still depends on the legal requirements and AT's decision; an agency cannot guarantee the outcome.
7. Risks and practical notes
- A NIF is not a substitute for a visa, an address or tax residence. If you later spend enough days in Portugal, or have a home that points to tax residence, you should ask AT within 60 days to update your registration to resident.
- Purpose, name and address must be genuine. Errors in the tax file are hard to correct and can get in the way of a bank account or a contract.
- After you receive a NIF, you will usually still need a Portal das Finanças password before you can view your file, join electronic notifications or manage a fiscal representative. Follow the official instructions in force at the time.
- An agency is not a government office. Read the authorisation, the representative arrangement and any renewal terms before you pay. Do not treat documents attached to an agency email as if they were the tax-authority website; check Portal das Finanças when you can.
- This guide compiles public official pages and one source post. It is not tax, legal or immigration advice. For a complex case, speak to a qualified lawyer or tax adviser in Portugal.
Carddoger summary
A Portuguese NIF is a nine-digit tax identification number issued by AT. The official application itself is free. If you are in Portugal, book an appointment at Finanças or a Loja do Cidadão. If you are abroad, the official online path is for a legal representative to file through e-balcão. The NIF Online service in the source post is a third-party agency; the homepage starting price is about €74.90, which is a service fee, not a tax. Before you pay, check whether they will be appointed as your fiscal representative and whether the plan auto-renews.
Appointing a fiscal representative is not required when the NIF is issued. Once a tax relationship with Portugal arises, non-EU residents usually have 15 days to appoint a representative or join electronic notifications on Portal das Finanças or ViaCTT. Self-employment in Portugal has a separate, mandatory VAT-representative rule that electronic notification does not replace. Official routes exist to appoint, change or end a representative; follow the AT leaflet and Article 19 of the General Tax Law.
A NIF is not residence, and it is not tax-resident status. Autoridade Tributária, Portal das Finanças and gov.pt as they stand on the day you apply take priority.
Sources
- Source post: artistd4qu, 2026-11-10 UTC
- AT: NIF page
- AT leaflet (July 2025): Tax identification number for foreign non-residents (PDF)
- AT: Appoint a tax representative (English)
- AT: General Tax Law, Article 19
- AT: Electronic notifications leaflet (PDF)
- gov.pt: Request a NIF for a natural person (updated 1 September 2026)
- gov.pt: How foreign nationals apply for a NIF and NISS (updated 2 September 2026)
- gov.pt: Appoint a fiscal representative
- Third-party agency (not official): NIF Online
- Related guides on this site: article 134, four European and Malaysian tax IDs, article 139, German Steuer-ID